For most people, keeping everyday savings in a regulated bank is much safer than holding the same amount in cryptocurrency. Banks are built to protect the face value of a deposit. Crypto offers no matching guarantee.
That does not mean banks carry no risk. It also does not mean crypto is unsafe in every way. The two protect against different kinds of problems.
This article uses recent figures from regulators, the FDIC, Chainalysis and Fidelity Digital Assets to compare them. It covers deposit insurance, bank failures, price swings, inflation, theft, scams and custody. Each section includes a chart, and most include a table.
Bank vs Crypto Safety at a Glance
The safest place for money depends on the risk you want to avoid. A bank deposit is built to keep its face value. Bitcoin is built around a fixed supply and ownership without a bank.
Take one question. Where should someone keep €20,000 they may need next year? A protected bank deposit is the clear answer.
Now ask which asset gives more independence from banks and monetary policy. Bitcoin makes a stronger case on that point.
| Risk | Insured bank deposit | Self-custodied Bitcoin | Crypto on an exchange |
|---|---|---|---|
| Bank or platform failure | Low | Not applicable | Medium |
| Deposit protection | Yes, within limits | No | Usually no |
| Price volatility | Very low in nominal terms | Very high | Very high |
| Inflation risk | Yes | Yes, but a different monetary model | Yes |
| Hacking or theft risk | Relatively low for the depositor | User carries much of the risk | Platform and user risk |
| Lost password or key | Usually recoverable | Potentially catastrophic | Account recovery usually available |
| Fraud protection and reversals | Often available | Usually not | Limited |
| Counterparty risk | Bank and banking system | Minimal if correctly self-custodied | The exchange |
| Government seizure or freeze risk | Possible | Harder with proper self-custody | Possible |
| Global 24/7 transfers | Limited | Strong | Strong but platform dependent |
| Long-term purchasing power certainty | No | No | No |
The last row matters. Neither cash nor crypto guarantees that your money will buy the same amount in the future. They simply fail in different ways.
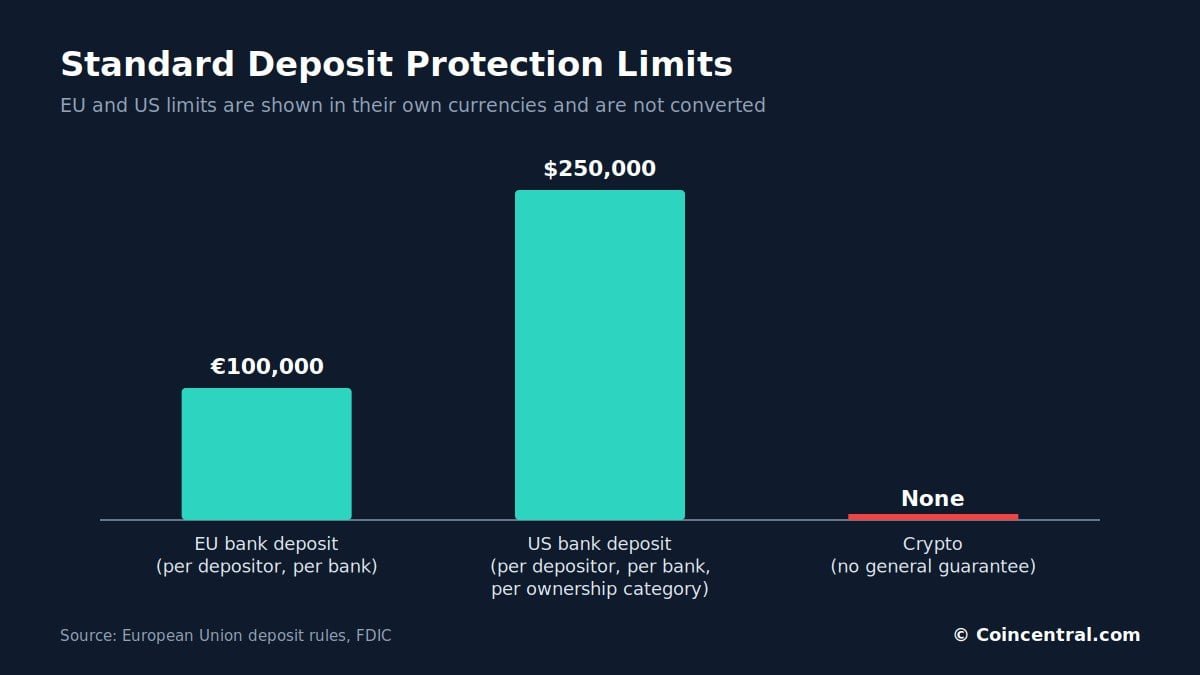
The biggest gap is deposit protection. The chart below shows the standard limits.
Deposit Insurance and Bank Failures
In the European Union, eligible deposits are generally protected up to €100,000 per depositor, per bank. Portugal applies the same limit through its Deposit Guarantee Fund. Banco de Portugal says current accounts, term deposits and several other deposit types are covered.
In the United States, the FDIC protects at least $250,000 per depositor, per insured bank, per ownership category. That covers checking accounts, savings accounts, money market deposit accounts and certificates of deposit. Crypto assets are not covered.
The UK’s Financial Conduct Authority gives a similar warning. Direct crypto investments are not protected by the Financial Services Compensation Scheme. The FCA says investors should be ready to lose all the money they put in.
| Region | Standard protection | What is covered |
|---|---|---|
| European Union | €100,000 per depositor, per bank | Eligible bank deposits |
| Portugal | €100,000 through the Deposit Guarantee Fund | Current accounts, term deposits and other types |
| United States | $250,000 per depositor, per insured bank, per ownership category | Checking, savings, money market deposit accounts and CDs |
| United Kingdom (crypto) | None under the FSCS | Direct crypto investments are not covered |
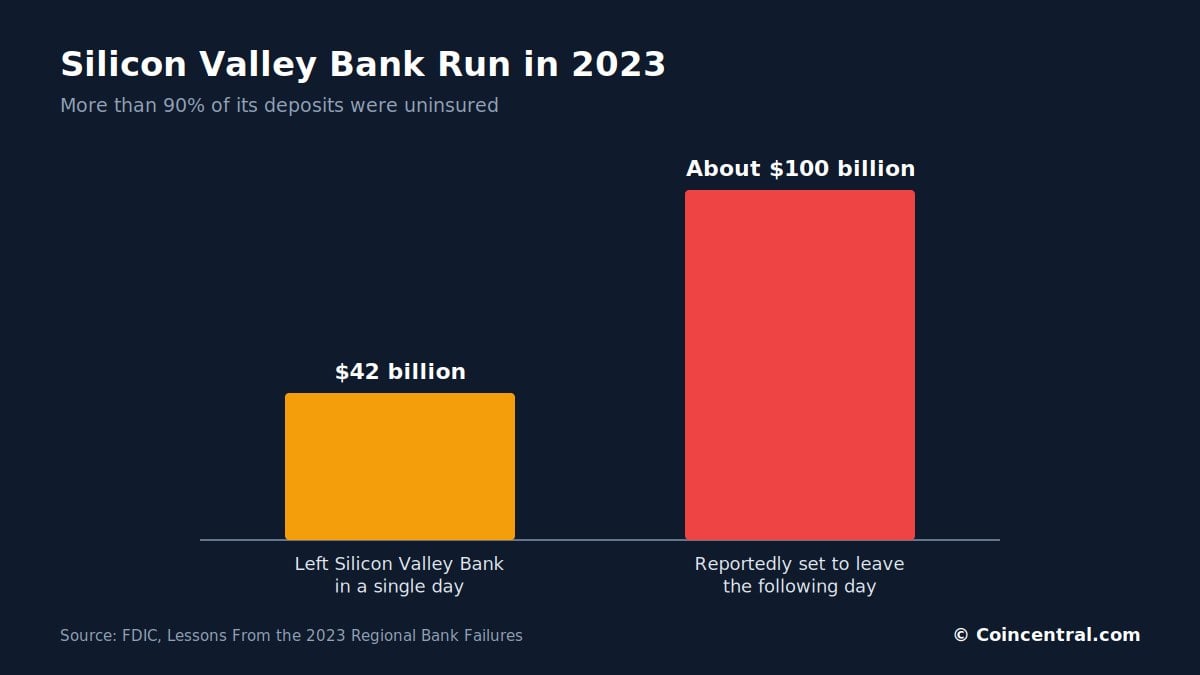
Bank failures do happen. Five FDIC-insured US banks failed in 2023, including Silicon Valley Bank and Signature Bank. At Silicon Valley Bank, more than 90% of deposits were uninsured.
About $42 billion left the bank in a single day. Another $100 billion was reportedly set to leave the next day. The bank failed, yet insured depositors were protected.
The FDIC says insured depositors usually get access to their covered funds within a few days, often by the next business day. A bank failing and a depositor losing insured money are not the same event.
Limits still matter. A person with €500,000 in one EU bank account normally has €100,000 of standard protection. A US depositor with $1 million in a simple account at one bank may have $250,000 of standard coverage.
The FDIC’s 2026 study found that depositors with large uninsured balances were more likely to run from Silicon Valley Bank, Signature Bank and First Republic than fully insured retail depositors. Savers below the limits face far less of this risk.
Bitcoin’s Biggest Risk Is Price Volatility
A bank balance does not normally move 20% in a month. Bitcoin can. That is the main reason it does not suit money needed on a set date.
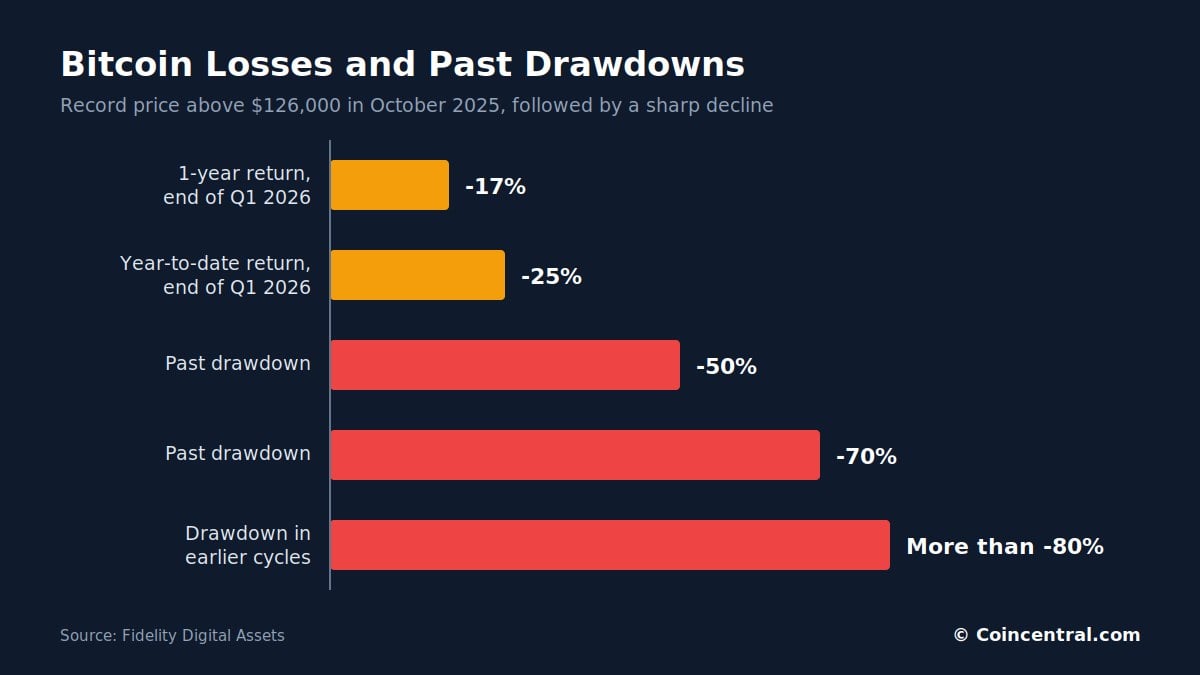
Fidelity Digital Assets reported that at the end of Q1 2026, Bitcoin’s trailing one-year return was about -17%. Its year-to-date return was about -25%. Solana fell by more.
Bitcoin reached a record above $126,000 in October 2025 and then dropped sharply. In the past it has seen drawdowns of 50%, 70% and, in earlier cycles, more than 80%.
| Measure | Figure |
|---|---|
| Trailing one-year return, end of Q1 2026 | About -17% |
| Year-to-date return, end of Q1 2026 | About -25% |
| Record price | Above $126,000 in October 2025 |
| Past drawdowns | 50%, 70% and more than 80% in earlier cycles |
Bitcoin has also posted strong long-term returns. Fidelity notes it has beaten traditional assets over several periods. Those gains did not come in a straight line.
Picture €30,000 saved for a house deposit next year. In a protected euro account it stays near €30,000 before interest and inflation. In Bitcoin it could become €45,000 or €18,000, and nobody knows in advance.
If Bitcoin falls from $100,000 to $50,000, you still own the same amount of BTC. Half of its dollar value is gone. No insurer covers the gap.
Inflation Hits Bank Savings, and Bitcoin Has a Fixed Supply
Banks lead on nominal safety. They do not protect purchasing power. Money in an account keeps its face value while prices rise.
Say you hold €100,000 in cash for ten years. If inflation averages 3% a year, the statement still shows €100,000. But it buys only what about €74,000 buys today.
There is no sudden crash on the banking app. The loss builds slowly through higher prices. Interest can offset some or all of it, depending on the rate and tax rules.
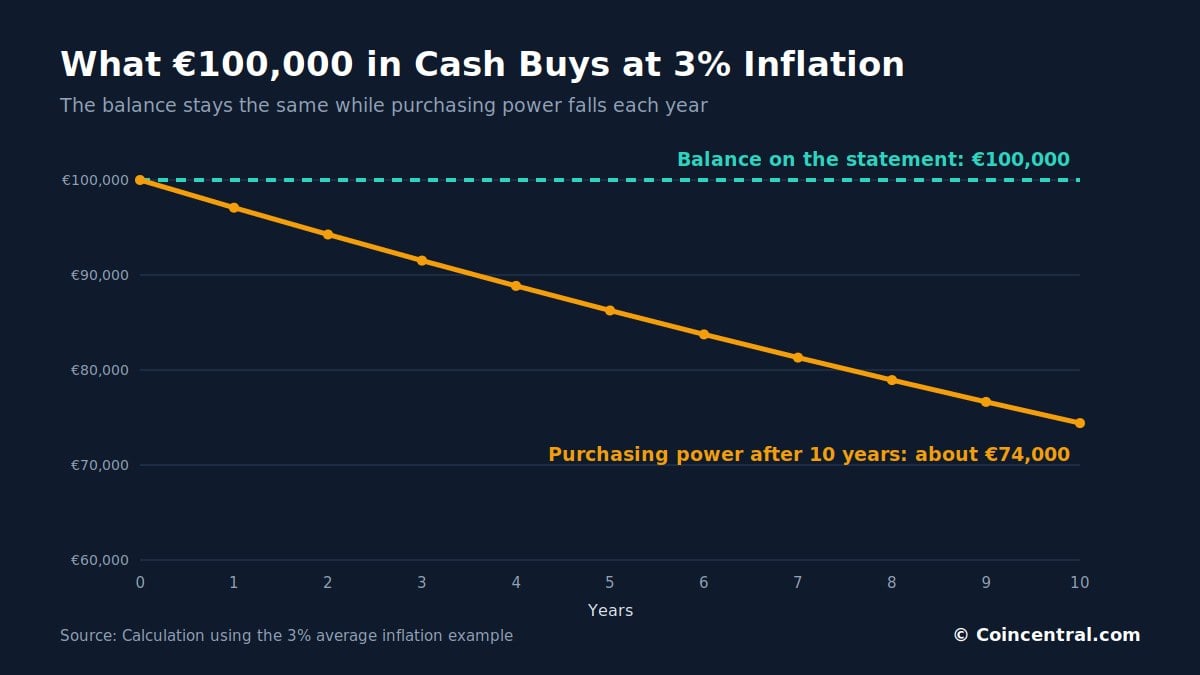
| Year | Balance on statement | Purchasing power at 3% inflation |
|---|---|---|
| 0 | €100,000 | €100,000 |
| 5 | €100,000 | About €86,000 |
| 10 | €100,000 | About €74,000 |
Bitcoin works differently. Its supply is capped at 21 million BTC. New issuance falls about every four years through the halving.
No central bank can create another 10 million BTC. That removes one risk, which is the supply being diluted by decision. It does not guarantee demand or price.
Fiat currencies are managed by central banks to meet goals such as stable prices. Savers therefore face a trade-off. Deposits offer short-term stability, while Bitcoin offers a rigid supply but large price swings.
Is Bitcoin a better inflation hedge? Possibly over long periods, but not reliably over short ones. Bitcoin can fall while consumer prices rise.
In a high-inflation year a saver might lose 2% to 4% of real purchasing power. A Bitcoin holder can lose 40% in several months.
Crypto Theft Statistics
Crypto security has improved, but theft remains large. Chainalysis estimates about $3.4 billion in crypto was stolen through hacks in 2025.
Personal wallet compromises made up about 20% of stolen value. That is roughly $713 million.
Chainalysis counted about 158,000 theft incidents in 2025, up from 54,000 in 2022. At least 80,000 individual victims were affected.
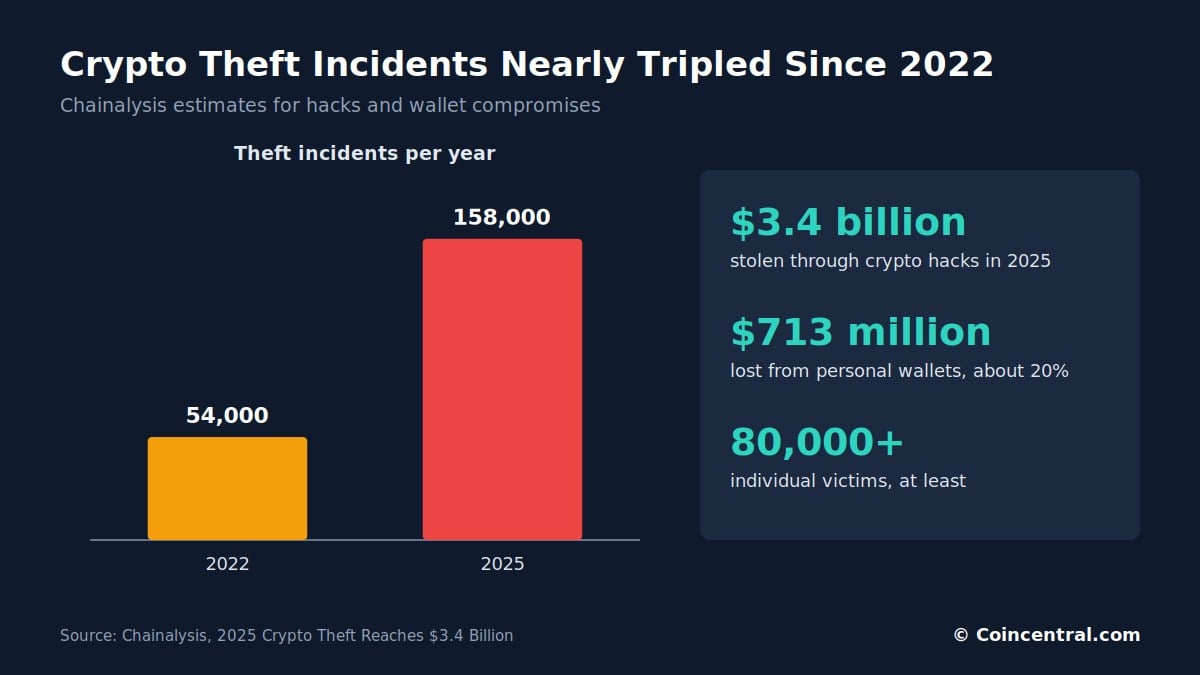
| Measure | Figure |
|---|---|
| Crypto stolen through hacks, 2025 | About $3.4 billion |
| Personal wallet losses, 2025 | About $713 million |
| Share of stolen value from personal wallets | About 20% |
| Theft incidents | About 158,000 in 2025, up from 54,000 in 2022 |
| Individual victims | At least 80,000 |
These numbers do not mean 20% of crypto users are hacked. They show that direct ownership brings a kind of security risk that an insured bank depositor does not face to the same degree.
Banks face cybercrime too. They deal with account takeovers, card fraud, phishing, data breaches, ransomware and insider fraud.
The difference is where liability sits. A customer is not normally expected to absorb a bank’s whole loss. Banks have capital rules, fraud controls, insurance, customer authentication, dispute procedures and deposit protection. Self-custody moves much of that duty to the individual.
Crypto Scam Statistics
Scams are larger than hacks. Chainalysis first found at least $14 billion flowing to known scam addresses in 2025. It projected the figure could pass $17 billion as more addresses are found.
The average scam payment rose from $782 in 2024 to $2,764 in 2025. Impersonation scams rose about 1,400% year over year.
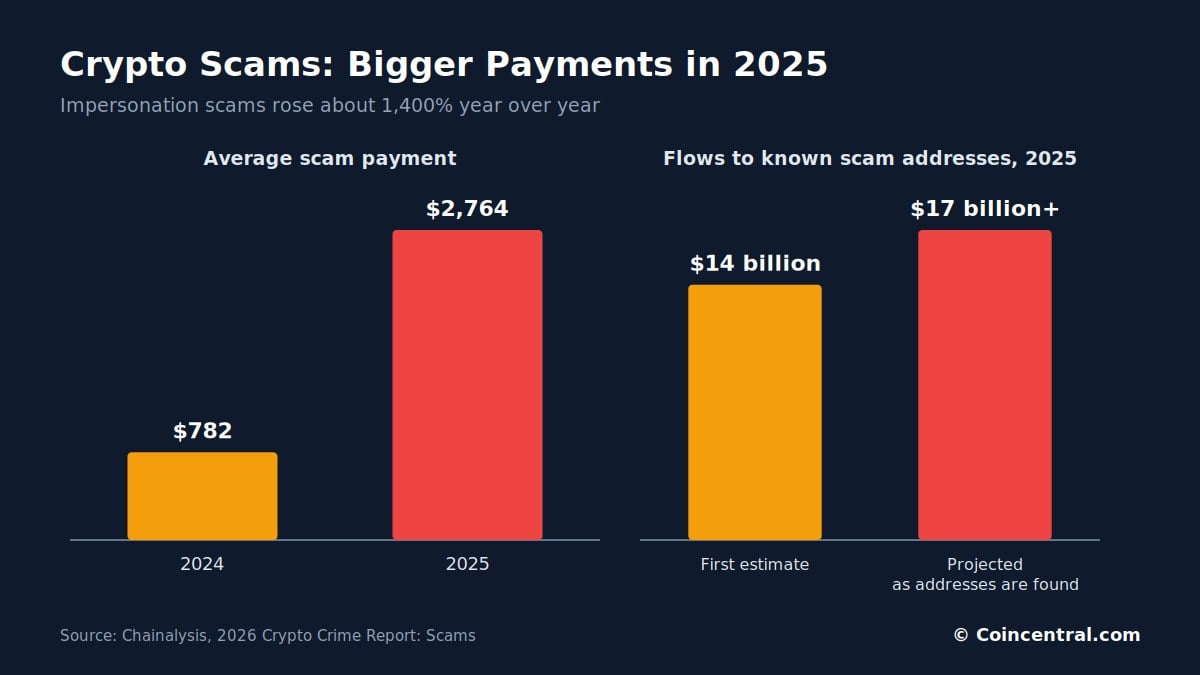
| Measure | 2024 | 2025 |
|---|---|---|
| Average scam payment | $782 | $2,764 |
| Flows to known scam addresses | Not given | At least $14 billion, projected above $17 billion |
| Impersonation scam growth | Not given | About 1,400% year over year |
Banks see fraud too. But bank and card systems often have ways to freeze suspicious transactions, challenge unauthorized payments or restore account access.
Crypto transactions are normally irreversible once confirmed. That makes mistakes and fraud costly. A payment sent to the wrong address or to a scammer is usually gone.
Self-Custody, Exchanges and Stablecoins
Bitcoin can be held without a bank or an exchange. With proper self-custody, the owner controls the private keys needed to spend it. If a bank or exchange fails, self-custodied Bitcoin is not affected.
That freedom has a cost. The owner becomes responsible for security. Forget a bank password and you can reset it, but lose the recovery phrase for a wallet with no backup and there may be no way back.
The Bitcoin network does not know your identity. It only recognizes valid cryptographic signatures. Nobody needs to give you permission to use your funds, and nobody is responsible for rescuing you.
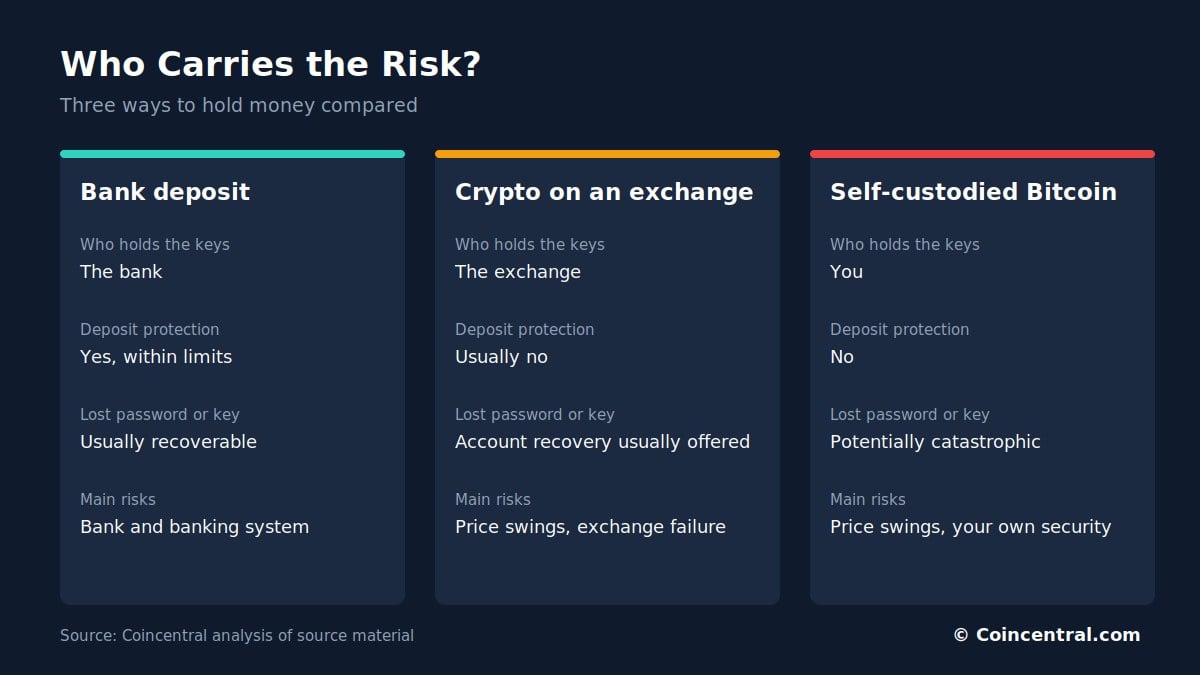
| Option | Who holds the keys | Main protection | Main weakness |
|---|---|---|---|
| Bank deposit | The bank | Deposit insurance within limits, dispute procedures | Inflation, losses above the limit |
| Crypto on an exchange | The exchange | Account recovery | Exchange failure, no guarantee |
| Self-custodied Bitcoin | The owner | No bank or exchange risk | Lost keys, theft, no reversals |
Crypto held on an exchange
Some people avoid key risk by leaving crypto on an exchange. Passwords can be recovered, and buying and selling is simple. But the exchange holds the private keys, and the customer has a claim against the company.
FTX showed what happens when that model fails. Customers thought they held crypto on a major global exchange, and the business collapsed into bankruptcy. Celsius, BlockFi and other firms taught similar lessons. That is why the phrase “Not your keys, not your coins” exists.
Compare €50,000 in an eligible Portuguese bank deposit with €50,000 of Bitcoin on an exchange. The deposit can be protected up to €100,000. The Bitcoin has no such guarantee, even if the app looks like online banking.
Stablecoins
Stablecoins such as USDC and USDT aim to stay close to $1. That removes most of Bitcoin’s price swings. It does not turn the token into an insured deposit.
Holders face issuer, reserve, blockchain, smart contract, wallet, depegging and regulatory risk. For plain cash savings, an insured bank account generally offers stronger protection. The strength of stablecoins is 24/7 digital settlement and cross-border transfer.
Where crypto has an edge
Bank accounts depend on the institution, national laws and payment systems. They can sometimes be frozen, garnished or restricted, or hit by capital controls. Properly self-custodied Bitcoin can move peer to peer without a bank’s permission.
For people under unstable banking systems or political repression, that can be a real form of resilience. For a saver in a stable EU country, it must be weighed against volatility and key management.
Matching Your Money to Your Goal
Think about money needed for rent, mortgage payments, food, medical bills, taxes, emergency repairs or tuition. The key traits are stable face value, quick access and low risk of permanent loss. Insured bank deposits do well on all three. Bitcoin and volatile altcoins do not.
The point of an emergency fund is not return. It is making sure the money exists when the emergency arrives.
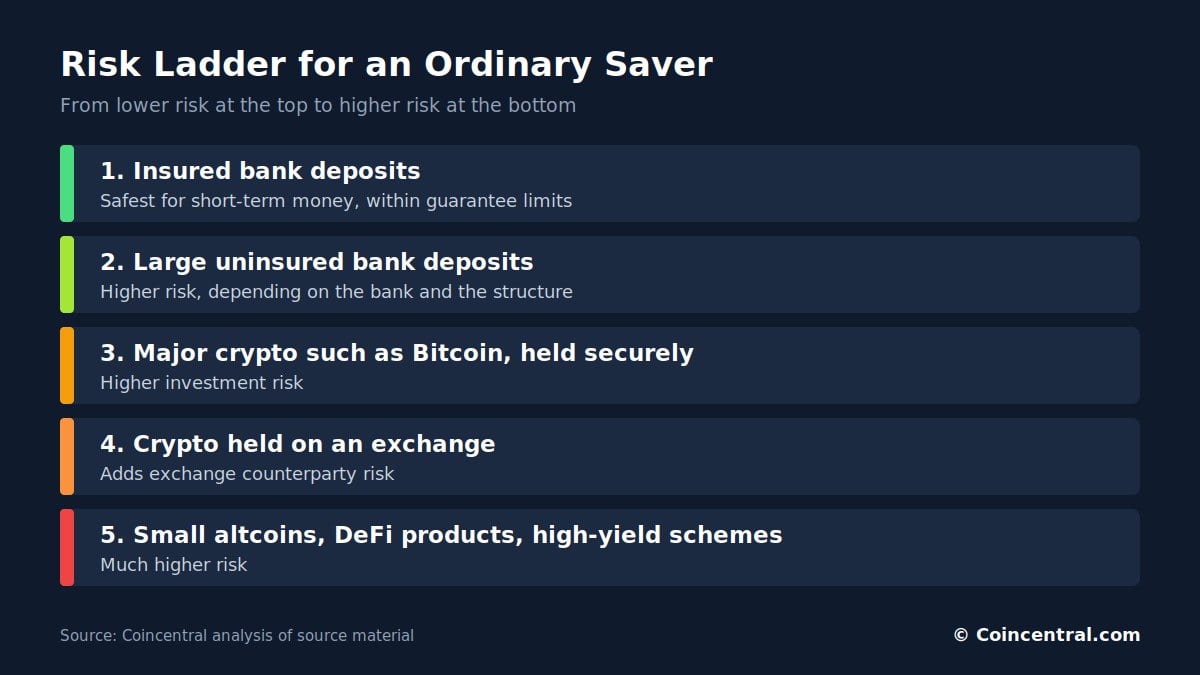
| Goal | Better fit |
|---|---|
| Emergency fund | Insured bank deposit |
| Money needed in the next few years | Insured bank deposit |
| Cash above the insurance limit | Spread across several banks, short-term government securities or regulated money-market products |
| Long-term money that can handle large swings | Bitcoin may fit as one part of a portfolio |
| Independence from the banking system | Properly self-custodied Bitcoin |
The picture changes for money that will not be needed for many years. A portfolio might hold cash, bonds, stocks, property and Bitcoin. Each plays a different role.
Cash gives liquidity and stable face value. Stocks give a share in company profits. Bonds give income and diversification. Bitcoin gives exposure to a scarce digital asset with high potential return and high risk.
Money above the insurance limit is a separate problem. Someone with €500,000 can spread eligible deposits across several banks, because the EU limit applies per bank. Bitcoin does not become a low-risk cash substitute just because a balance passes the limit.
It also matters which crypto you mean. Bitcoin, Ethereum, a dollar stablecoin and a new memecoin carry very different risks. Small coins can lose 99%, lose liquidity, be abandoned, be exploited or be delisted. Bitcoin has a longer history and deeper liquidity.
Over 20 years, neither option guarantees purchasing power. Cash is eroded slowly by inflation. Bitcoin could rise a lot, stall or fall, and no promise exists that future buyers will pay more.
The Bottom Line
Is crypto safer than keeping money in the bank? For cash savings, emergency funds and money needed in the next few years, no. A properly insured bank deposit is considerably safer.
In the EU, qualifying deposits are generally guaranteed up to €100,000 per depositor, per bank. In the US, eligible deposits are normally covered up to $250,000 per depositor, per insured bank, per ownership category. Crypto has no comparable general guarantee.
Bitcoin can fall sharply, keys can be lost, exchanges can fail and wallets can be compromised. Chainalysis estimated $3.4 billion was stolen through hacks in 2025. Scams may have cost about $17 billion that year.
Still, self-custodied Bitcoin removes dependence on a commercial bank. It is a scarce, globally transferable asset that no central bank can create at will. That can make it useful as a long-term investment or a hedge against some financial-system risks.
A €50,000 example
Say someone has €50,000. In a bank it stays inside the €100,000 guarantee, keeps its face value and may earn interest. Inflation is the main long-term risk.
In Bitcoin on a hardware wallet, there is no bank risk. But the value could become €75,000, €100,000 or €200,000. It could also fall to €35,000 or €20,000, and the owner must secure the keys.
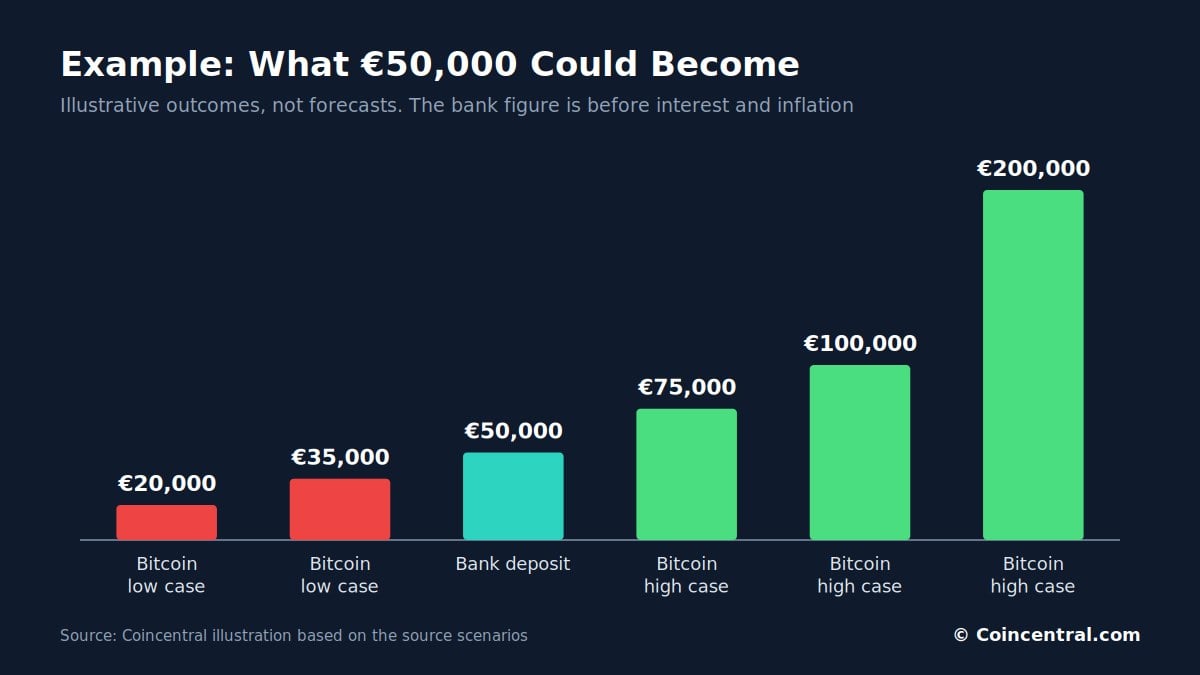
| Option | Possible outcome in the example | Main risk |
|---|---|---|
| Bank deposit | Stays at €50,000 before interest | Inflation |
| Self-custodied Bitcoin | From €20,000 to €200,000 | Price swings and key security |
| Bitcoin on an exchange | From €20,000 to €200,000 | Price swings and exchange failure |
On an exchange, the holder takes Bitcoin’s price risk plus exchange risk. For capital preservation over one or two years, the bank has a large safety edge.
For most people the better path is to use both for what they do best. Keep short-term and emergency money in protected deposits. Put only the amount that can handle large swings into Bitcoin or other crypto.
Banks are generally safer for preserving money you need. Bitcoin may offer more upside and more financial independence. Those are useful traits, but they are not the same as safety.
This article is for information only and is not financial advice.
Sources
- European Union: Deposit Protection Rules
- Banco de Portugal: Deposit Guarantee
- Federal Deposit Insurance Corporation: Deposit Insurance
- FDIC: Dissecting Depositor Flight, 2026
- FDIC: Lessons From the 2023 Regional Bank Failures
- Financial Conduct Authority: Risks of Investing in Cryptoassets
- Chainalysis: 2025 Crypto Theft Reaches $3.4 Billion
- Chainalysis: 2026 Crypto Crime Report: Scams
- Fidelity Digital Assets: Signals Report Q2 2026
- Fidelity Digital Assets: Is Bitcoin’s Four-Year Cycle Over?
The post Is Crypto Safer Than a Bank? Key Statistics for 2026 appeared first on Blockonomi.
This articles is written by : Nermeen Nabil Khear Abdelmalak
All rights reserved to : USAGOLDMIES . www.usagoldmines.com
You can Enjoy surfing our website categories and read more content in many fields you may like .
Why USAGoldMines ?
USAGoldMines is a comprehensive website offering the latest in financial, crypto, and technical news. With specialized sections for each category, it provides readers with up-to-date market insights, investment trends, and technological advancements, making it a valuable resource for investors and enthusiasts in the fast-paced financial world.